


You choose to apply for CIMA CIMA Certification because you know the society is full of competition and challenges. If you do not want Financial Reporting exam to become your stumbling block, you should consider our Financial Reporting test for engine or F1 VCE test engine. Our Test4Engine is the leading position in this line and offer high-quality software test engine which can help you go through your examination. If you have no confidence for the CIMA Financial Reporting exam, our Financial Reporting test for engine will be your best select.

We have three versions for each exam dumps that: PDF dumps, Soft test engine, and APP on-line test engine. Totally the APP on-line test for engine is the most popular. Most candidates think about F1 test for engine or Financial Reporting VCE test engine, they will choose APP on-line test engine in the end. The APP on-line test engine has many functions below.
1. Financial Reporting APP on-line test engine includes the exam practice questions and answers. You can practice whenever you want. F1 VCE test engine includes 80% or so questions & answers of the real test. It is the foundation for passing exam. Of course, the PDF dumps & Soft test engine also have this function. (Financial Reporting test for engine)
2. Financial Reporting APP on-line test engine can imitate the real test; it can set timed test, mark your performance and point out your mistakes. (F1 test for engine) It is really like the real test. It is helpful for clearing up your nervousness before test. The soft test engine also has this function but the PDF dumps do not.(Financial Reporting VCE test engine)
3. Financial Reporting APP on-line test engine can be installed in all operate systems. You can download Financial Reporting VCE test engine in your computers, iPhones, iWatch, MP4 or MP5 and so on. You can learn any time and any place you like. The soft test engine can just be installed in personal computers.
4. Statistically speaking, Financial Reporting APP on-line test engine is also stable than the soft test engine. It is more powerful.
Besides, you may doubt about our service. Yes, we guarantee your money and information safety. We make sure that "No Pass, No Pay". Our Financial Reporting test for engine can assist you go through the examination surely, meanwhile, our service will 100% satisfy you.
1. Our working time is 7*24, we will serve for you any time even on official holiday. You email or news about F1 test for engine will be replied in 2 hours. Your questions & problems will be solved in 2 hours. After payment, you will receive our Financial Reporting test for engine & Financial Reporting VCE test engine soon.
2. We have professional IT staff who updates exam simulator engine every day so that all F1 test for engine we sell out is latest & valid. Also we have a strict information system which can guarantee your information safety.
3. We support Credit Card payment so that your account and money will be safe certainly, you are totally worry-free shopping. We guarantee our Financial Reporting test for engine will assist you go through the examination surely. If you fail the exam unluckily we will refund you all the money you paid us unconditionally in one week. You get what you pay for.
More details please feel free to contact with us, we are pleased to serve for you. Give me a chance, I send you a success. Financial Reporting test for engine & F1 VCE test engine will indeed be the best helper for your CIMA F1 exam. If you choose us, you will 100% pass the exam for sure.
CIMA F1 Exam Syllabus Topics:
| Section | Objectives |
|---|---|
| Financial Statement Analysis | - Performance analysis
|
| Accounting Standards Application | - Basic application of IFRS standards
|
| Financial Reporting Fundamentals | - Financial Statements Preparation
|
CIMA Financial Reporting Sample Questions:
CDE has been offering its customers a 50-day credit period, but now wants to improve its cash flow.
CDE is proposing to offer a 2% discount for payment in 20 days. "
Assume a 365-day year and an invoice value of $100
Which of the following is the effective annual interest rate CDE will incur for this action?
- A. 49.8%
- B. 15.9%
- C. 27.9%
- D. 44.6%
Correct Answer: C 🗳️
AB has been asked to analyze the receivables days of an entity with a view to improving the working capital cycle.
The following results have been produced for receivable days: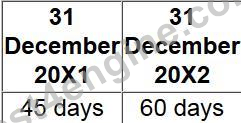
Which of the following is NOT an explanation of why the days have increased?
- A. An inexperienced credit controller was employed in the last few months of year ended 31 December and requires substantial training.
- B. The entity has made substantial sales to overseas entities in the last few months of the year ended 31 December 20X2.
- C. The entity has transferred all receivables collections to a factoring agency during 20X2.
- D. The entity has increased turnover for year ended 31 December 20X2 by offering extended credit terms.
Correct Answer: C 🗳️
Statements of financial position for YZ, BC and DE at 31 March 20X2 include the following balances: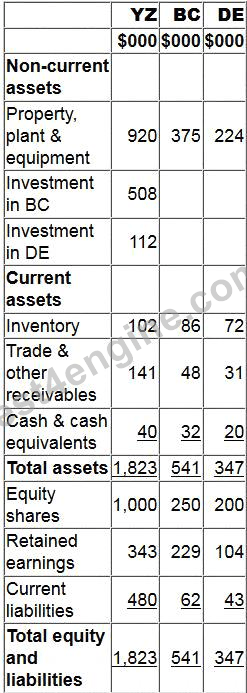
YZ purchased 90% of BC's equity shares for $508,000 on 1 January 20X2. On 1 January 20X2 BC's retained earnings were $183,000. YZ uses the proportion of net assets method to value non-controlling interest at acquisition.
YZ purchased 30% of DE's equity shares on 1 April 20X1 for $112,000. DE's retained earnings at 1 April
20X1 were $88,000.
On 1 February 20X2 YZ sold goods to BC for $28,000 at a mark up of 25% on cost. All the goods were still in BC's inventory at 31 March 20X2.
Calculate the value of inventory that will be included in YZ's consolidated statement of financial position at 31 March 20X2.
Give your answer to the nearest whole $.
Correct Answer:
$182400
AB has prepared its financial statements for the year ended 31 July 20X5. On 15 September 20X5 a major fraud was uncovered by the external auditors which had taken place during the year to 31 July 20X5 The financial statements have not yet been authorised In accordance with IAS 10 Events After the Reporting Period, AB should treat the fraud as: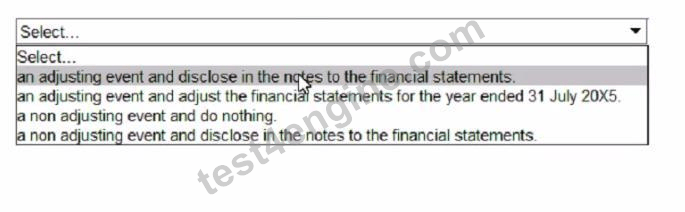
Correct Answer:
Pending
The legislation in Country S provides for an indexation allowance in the calculation of capital tax. STU operates in Country S where the indexation factor for the period 1 January 20X1 to 31 December 20X6 is 20% STU purchased a building for $64,000 on 1 January 20X1, incurring legal fees of $4,000. STU sold the building for $86,000 on 31 December 20X6 before selling fees of $3,500 What is the chargeable capital gam arising on STU's disposal of the building?
- A. S11,600
- B. $200
- C. $5,700
- D. S900
Correct Answer: D 🗳️


