


[2025] CGFM Actual Exam Dumps, CGFM Practice Test
Test4Engine CGFM dumps & AGA CGFM sure practice dumps
NEW QUESTION # 21
Which of the following disbursement techniques can be used to ensure timely payments?
- A. drafts
- B. checks
- C. bank cards
- D. warrants
Answer: A
Explanation:
What Are Disbursement Techniques?
* Disbursement techniques refer to the methods used by organizations to pay vendors or settle financial obligations. The timeliness of payments depends on the technique used.
Why Are Drafts the Best Option for Timely Payments?
* Adraftis a payment instrument issued by an organization's bank, drawn against its account, and typically includes specific payment timing instructions.
* Drafts allow the payer to specify the timing of payments, ensuring they are made on time.
Why Other Options Are Incorrect:
* A. Warrants:Warrants authorize payments but do not ensure timeliness as they require additional processing before funds are disbursed.
* B. Checks:Checks rely on postal delivery and clearing times, which may delay payments.
* D. Bank cards:While convenient, bank cards are typically used for immediate payments, not for ensuring future timely disbursements.
References and Documents:
* Treasury Financial Manual:Highlights drafts as a disbursement tool for controlling the timing of payments.
* GAO Cash Management Guide:Discusses the benefits of drafts in ensuring timely payments.
NEW QUESTION # 22
The National Performance Management Advisory Commission established a comprehensive framework that incorporates performance measurement into the
- A. budget process.
- B. audit procedures.
- C. internal control plan.
- D. financial statements.
Answer: A
Explanation:
National Performance Management Advisory Commission Framework:
* TheNational Performance Management Advisory Commissiondeveloped a comprehensive framework to integrateperformance measurementinto government operations.
* One of its primary goals was to incorporate performance metrics into thebudget processto align resource allocation with program outcomes.
* This ensures that budgeting decisions are informed by program performance, improving efficiency and accountability.
Why the Budget Process?
* By linking performance to budgeting, governments can prioritize funding for programs that demonstrate effectiveness and reduce funding for underperforming initiatives.
Why Other Options Are Incorrect:
* A. Internal control plan:Internal controls focus on risk management, not incorporating performance measurement.
* B. Financial statements:Performance metrics are not reported in financial statements, which focus on financial position and results.
* C. Audit procedures:Audits verify financial accuracy and compliance but do not incorporate performance measurement.
References and Documents:
* National Performance Management Advisory Commission Report (2010):Recommends integrating performance measurement into the budget process.
* GAO Guide on Performance Budgeting:Explains how performance metrics inform budget decisions.
NEW QUESTION # 23
All of the following are core banking services EXCEPT:
- A. Security services
- B. Reconciliation Services
- C. Investment management
- D. Concentration and Zero balance
Answer: C
NEW QUESTION # 24
For financial audits, generally accepted auditing standards require that auditors accomplish all of the following tasks EXCEPT
- A. make the audit report available to the public.
- B. obtain sufficient appropriate audit evidence.
- C. supervise any assistants.
- D. adequately plan the work.
Answer: A
Explanation:
What Do Generally Accepted Auditing Standards (GAAS) Require for Financial Audits?GAAS outlines specific requirements for auditors conducting financial audits, including:
* Adequately Planning the Work (Option A):Proper planning ensures that audits are efficient and thorough.
* Obtaining Sufficient, Appropriate Audit Evidence (Option C):This is critical to support the auditor' s opinion on the financial statements.
* Supervising Assistants (Option D):Supervising any audit staff ensures that work is performed in accordance with standards.
What Does GAAS Not Require?
* GAAS does not specifically require auditors to make the audit report available to the public (Option B).
While making reports available to the public may be required by other laws, regulations, or organizational policies, it is not a standard requirement under GAAS. The decision to make the report public often lies with the audited entity or governing bodies.
References and Documents:
* AICPA Statements on Auditing Standards (SAS):The foundational standards that define GAAS requirements.
* GAGAS (Yellow Book):While GAGAS may have additional reporting requirements, it does not mandate public access to the audit report unless stipulated by law.
NEW QUESTION # 25
With respect to capital leas the cops, the rating analyst evaluates:
- A. The risk of non-appropriation
- B. The essentialities of the asset
- C. General creditworthiness
- D. All of these
Answer: D
NEW QUESTION # 26
A city has an EMF of 0.80. Its premium at 1.0 would have been $10,000. Therefore, its actual premium is:
- A. $8000
- B. None of these
- C. $8800
- D. $800
Answer: A
NEW QUESTION # 27
Based on the data below, what can be concluded about outsourcing print job?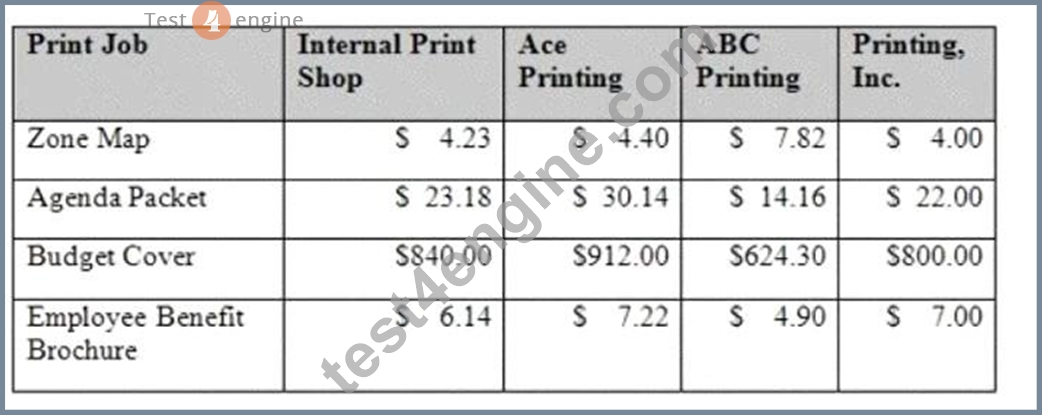
- A. Outsourcing printing is necessary.
- B. ABC Printing should be awarded the outsourcing contract.
- C. Outsourcing printing is feasible.
- D. It is better to keep the printing in-house.
Answer: C
Explanation:
* Understanding the Scenario:The table compares the costs of four printing jobs performed by an
"Internal Print Shop" versus three external vendors (Ace Printing, ABC Printing, and Printing, Inc.).
Eachvendor's pricing varies by print job type. The task is to evaluate whether outsourcing (hiring external vendors) is a reasonable alternative to keeping the work in-house.
* Key Considerations in Outsourcing:According to governmental accounting principles and budgeting practices outlined by theAssociation of Government Accountants (AGA), the decision to outsource should consider:
* Cost-effectiveness: Does outsourcing reduce costs without compromising quality or service delivery?
* Operational efficiency: Can outsourcing free up internal resources for other priorities?
* Comparative pricing: How do external vendor rates compare to internal costs for identical services?
* Analysis of the Print Jobs:Let's break down the cost comparison for each print job:
* Zone Map:Internal cost = $4.23.Cheapest vendor = Printing, Inc., at $4.00.Outsourcing is cheaper for this job.
* Agenda Packet:Internal cost = $23.18.Cheapest vendor = Printing, Inc., at $22.00.Outsourcing is cheaper for this job.
* Budget Cover:Internal cost = $840.00.Cheapest vendor = ABC Printing, at $624.30.Outsourcing is significantly cheaper for this job.
* Employee Benefit Brochure:Internal cost = $6.14.Cheapest vendor = ABC Printing, at $4.90.
Outsourcing is cheaper for this job.
* Conclusion Based on Analysis:
* Across all four print jobs, the lowest-cost external vendor always beats the Internal Print Shop's costs.
* From abudgetary perspective, outsourcing is feasible as it offers cost savings across all jobs.
* Why Not A, C, or D?:
* Option A(Keep printing in-house): Incorrect, as in-house costs are consistently higher than the cheapest external vendor.
* Option C(Outsourcing is necessary): Incorrect, as feasibility doesn't mean necessity; internal printing is still an option if other factors (like quality or control) outweigh costs.
* Option D(Award contract to ABC Printing): Incorrect, since the best vendor depends on the job (e.g., Printing, Inc. is cheaper for Zone Map and Agenda Packet).
References:
* Association of Government Accountants (AGA),Government Financial Manager Certification Study Guide: Budgeting, Cost Accounting, and Auditing Principles.
* Government Finance Officers Association (GFOA),Best Practices in Outsourcing and Procurement.
* Federal Accounting Standards Advisory Board (FASAB),Cost Accounting Standards for Governmental Operations.
NEW QUESTION # 28
are in anticipation of improved market conditions in which to issue long- term debt. It typically matures within 15-45 days.
- A. Variable rate demand notes (VRDNs)
- B. Tax-exempt commercial paper (TECP)
- C. Revenue anticipation notes (RANs)
- D. Bond anticipation notes (BANs)
Answer: B
NEW QUESTION # 29
What is the present value of $25,000 to be received 10 years from today if the opportunity rate is 4%, the current tax rate is 1% and the expected future value is 9%?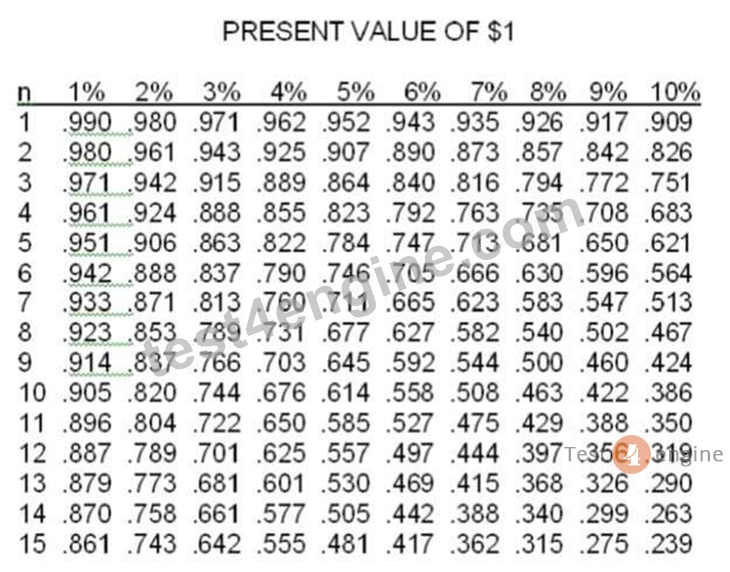
- A. $15,295
- B. $ 9,706
- C. $16,900
- D. $10,550
Answer: C
NEW QUESTION # 30
Risks are not assumed should, if possible, be transferred either by a .
- A. None of these
- B. Waiver of subrogation
- C. Hold-harmless contract clause
- D. Both of these
Answer: D
NEW QUESTION # 31
The noteworthy and most important thing in active investment by governments is:
- A. None of these
- B. Cash forecast
- C. Portfolio management
- D. Sector Allocation
Answer: B
NEW QUESTION # 32
A material weakness in internal control over financial reporting is defined as a deficiency that
- A. results in a misstatement to the basic financial statements.
- B. results in a material misstatement in other accompanying financial information.
- C. did not allow management to perform their assigned responsibility to prevent, detect and correct misstatements in a timelymanner.
- D. creates a reasonable possibility of a material misstatement to the financial statements that will not be detected in a timely manner.
Answer: D
Explanation:
Definition of a Material Weakness:According to auditing standards, a material weakness in internal control over financial reporting is a deficiency or combination of deficiencies that creates a reasonable possibility of a material misstatement in the financial statements that will not be prevented or detected on a timely basis.
Key Characteristics of a Material Weakness:
* Reasonable Possibility:The likelihood of a misstatement is more than remote but less than certain.
* Material Misstatement:The error or omission could impact the decisions of users relying on the financial statements.
* Timely Detection:The deficiency allows errors to go undetected for an extended period, potentially affecting financial statement reliability.
Why Other Options Are Incorrect:
* A.A misstatement in the basic financial statements may result from a material weakness, but the definition focuses on the reasonable possibility, not the actual result.
* B.A material weakness impacts the financial statements, not "other accompanying financial information."
* C.While timely detection is part of the issue, the definition focuses on the reasonable possibility of a misstatement, not management's inability to perform specific duties.
References and Documents:
* GAAS (AICPA SAS No. 115):Provides the formal definition of material weaknesses and guidance for auditors in evaluating control deficiencies.
* COSO Framework:Emphasizes the need for effective internal controls to mitigate material misstatement risks.
NEW QUESTION # 33
Gas, taxes restricted for road maintenance and repair, property taxes restricted for downtown development, property taxes restricted for fire tax districts and state tobacco settlement funds restricted for smoking reduction and economic development are settled by Government with the help of:
- A. Special revenue funds
- B. None of these
- C. Major Federal Government Funds
- D. Financial sector Funds
Answer: A
NEW QUESTION # 34
A STRIP (Separate individual interest and principal payments) is known as:
- A. Zero-coupon
- B. Individual-coupon
- C. Callable
- D. Floaters
Answer: A
NEW QUESTION # 35
and
debt issuance, governments must disclose information
regarding their debt and financial condition to the municipal securities market, including the preliminary Official Statement, the audited financial reports, the feasibility study, and other documents relating to the bond sale.
- A. During, after
- B. None of these
- C. Before, after
- D. It depends
Answer: A
NEW QUESTION # 36
Internal controls are the primary responsibility of:
- A. management.
- B. external auditors.
- C. internal auditors.
- D. the financial systems.
Answer: A
NEW QUESTION # 37
Which of the following is not included in general guidelines for a diversified investment portfolio?
- A. Do not over-concentrate securities from a specific issue or business sector
- B. never invest in readily liquid securities
- C. Invest in securities that have varying maturities
- D. Limited investment in securities with higher credit risk
Answer: B
NEW QUESTION # 38
Performance measures that report the results of providing goods or services are known as
- A. output measures.
- B. outcome measures.
- C. activity measures.
- D. workload measures.
Answer: A
Explanation:
* Definition of Output Measures:
* Output measures trackthe results of providing goods or services, such as the number of items produced or services delivered.
* These measures focus onquantityrather than quality or outcomes.
* Explanation of Answer Choices:
* A. Activity measures: Incorrect. Activity measures refer to inputs or processes, not results.
* B. Outcome measures: Incorrect. Outcome measures assess the impact or effectiveness of a program, not the quantity of goods/services provided.
* C. Output measures: Correct. Output measures focus on results (e.g., number of services delivered).
* D. Workload measures: Incorrect. Workload measures assess the volume of work performed but do not necessarily report on the results.
References:
* GASB,Performance Measurement Concepts.
* GAO,Performance Auditing Standards and Guidance.
NEW QUESTION # 39
Which of the following best suites this Question mark?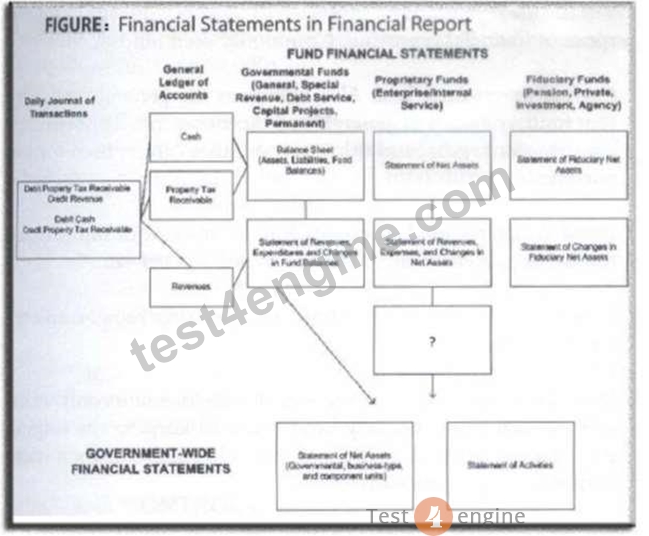
- A. None of these
- B. Statement of Expenditures
- C. Interim statement
- D. Statement of cash flows
Answer: D
NEW QUESTION # 40
......
CGFM Actual Questions and Braindumps: https://www.test4engine.com/CGFM_exam-latest-braindumps.html
Pass CGFM Exam with Updated CGFM Exam Dumps PDF 2025: https://drive.google.com/open?id=1cN1CrVXNatbTOpDaGOEsiEOTojp9yN0J